Contract Signed Before January 20, 2025? How to Tell If You Still Get 100% Bonus Depreciation
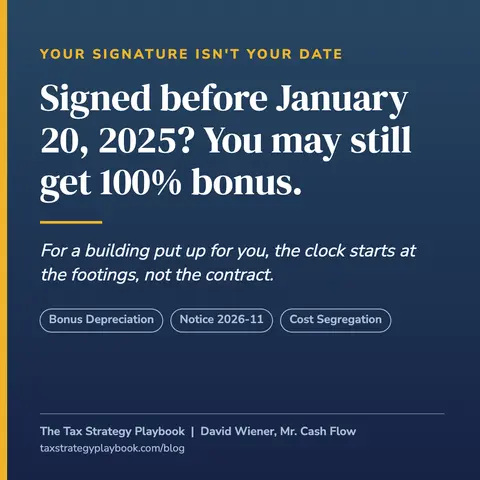
TL;DR: Signing a contract before January 20, 2025 does not always lock you out of 100% bonus depreciation. The law looks at when you acquired the property, and the IRS has detailed rules for that date. If you bought a finished building, the date can be later than the day you signed, because cancellation periods and contingencies push it forward. If a builder put up the property for you, the contract date usually doesn't count at all. What counts is the day real construction began. And if construction did start before the cutoff, an election can still give pieces added later the full 100%. Whatever is left on the old rules gets 20% bonus if it's placed in service in 2026, and none in 2027.
I covered this deadline briefly in this week's episode on what the election did and didn't change for bonus depreciation. Listen to the full conversation for the three-bucket test on every post-election tax headline, the factory building deadline, and why waiting for higher rates is a weak bet. This post takes one slice of it, the pre-2025 contract, and walks through the rules in full.
Key Takeaways
- The One Big Beautiful Bill Act gives 100% bonus depreciation to property acquired after January 19, 2025. Property acquired earlier stays on the old phase-down schedule.
- For a purchase, the IRS acquisition date is the latest of four dates: signing, enforceability, the end of any cancellation period, and the day all contingencies are met.
- A contract that caps the seller's damages below 5% of the price isn't a "binding contract" under the rules. Neither is a letter of intent or an option.
- For a building put up for you, the acquisition date is when physical work of a significant nature begins, not when you signed with the builder.
- If construction began before January 20, 2025, a component election can still give 100% to pieces acquired or started after January 19, 2025.
- For whatever stays on the old schedule, the placed in service date decides the rate: 20% in 2026, nothing in 2027.
What does the law actually say about a pre-2025 contract?
It says the contract date controls, but it doesn't say which date the contract was made.
Section 70301(c) of the One Big Beautiful Bill Act made the 100% rule apply to "property acquired after January 19, 2025." It then adds that "property shall not be treated as acquired after the date on which a written binding contract is entered into for such acquisition." That's the sentence behind every warning you've heard about contracts signed in late 2024.
But the statute stops there. It doesn't define a written binding contract. It doesn't say what happens when the deal has an inspection period. It doesn't say how to date a building that a contractor puts up for you over two years.
The IRS filled that gap with Notice 2026-11, released in January 2026. The notice tells taxpayers to apply the existing regulations, Treasury Regulation 1.168(k)-2(b)(5), "by substituting 'January 19, 2025' for 'September 27, 2017' each place it appears." Those regulations were written for the 2017 version of this same cutoff. So the rules for finding your acquisition date are not new. They're the 2017 rules with new dates.
The notice is interim guidance. Treasury and the IRS say proposed regulations will follow and are expected to match it. If you rely on the notice, it asks you to follow all of it for every eligible property in those years. You can't keep the parts you like and skip the rest.
I bought a building under a contract I signed in 2024. When did I acquire it?
Later than you might think. Under Regulation 1.168(k)-2(b)(5)(ii)(B), the acquisition date for property bought under a written binding contract is "the later of" four dates:
- The date the contract was entered into.
- The date it became enforceable under state law.
- If it has cancellation periods, the date they all end. The regulation defines a cancellation period as "the number of days stated in the contract for any party to cancel the contract without penalty."
- If it has contingency clauses, the date all those conditions are met. A contingency clause here is one with a condition or action "within the control of any party."
Think about how most commercial deals are written. You sign. Then you get a due diligence period, often 30 to 60 days, when you can walk away and get your deposit back. Under the regulation's words, that's a cancellation period, and the acquisition date can't come before it ends. Sign on December 10, 2024 with a 60-day inspection period, and the latest of those dates lands in February 2025. That's on the 100% side of the line.
There's a second test hiding in the definition. Under Regulation 1.168(k)-2(b)(5)(iii)(A), a contract is binding only if it "does not limit damages to a specified amount." A liquidated damages clause does exactly that. But the same paragraph says a cap of "at least 5 percent of the total contract price" isn't treated as a limit. So if the seller's only remedy is keeping an earnest money deposit worth 2% of the price, the contract may not be binding at all under these rules.
When the contract isn't binding, a different rule takes over. Under Regulation 1.168(k)-2(b)(5)(v), you acquire the property on the date you paid or incurred "more than 10 percent of the total cost of the property, excluding the cost of any land." On a typical purchase, that's the closing.
The same section closes two doors. "A letter of intent for an acquisition is not a binding contract." And "an option to either acquire or sell property is not a binding contract."
None of this lets you rewrite history. The test runs on what the contract said and what actually happened, and an examiner can ask for both. Pull the signed contract, every amendment, and the dates the inspection and financing periods ended. Then have your tax professional, and your real estate attorney if the wording is unclear, read them against the regulation before you assume the old schedule applies.
My contractor started a building for me. Does my construction contract date count?
Usually not. Most people get this backwards.
Regulation 1.168(k)-2(b)(5)(iv)(A) treats property built for you under a written binding contract, signed before work starts, as property you built yourself. Self-built property is dated by when construction begins, not when anyone signed. The regulation spells out what happens when the contract came first. If you sign with a builder before the cutoff and construction "begins after" the cutoff, you meet the acquisition test.
So when did construction begin? Under paragraph (b)(5)(iv)(B), it's "when physical work of a significant nature begins." Planning, design, financing, and permits don't count. The regulation's own example is a retail fuel outlet. Construction starts with "excavation for footings, pouring the pads for the outlet, or the driving of foundation pilings into the ground." Clearing the site and soil testing don't start the clock.
There's also a safe harbor. You can treat physical work as starting when you've paid or incurred "more than 10 percent of the total cost of the property, excluding the cost of any land and preliminary activities." If the builder is doing the work, that 10% test is measured by what you, the owner, have paid or incurred.
Take a construction contract signed in November 2024 with footings poured in March 2025. Under these rules, the building's qualifying parts were acquired after January 19, 2025. The pre-2025 signature doesn't put you on the old schedule.
What if construction started before January 20, 2025?
Then most of the project stays on the old schedule. But not necessarily all of it.
Section 3.05 of Notice 2026-11 brings back the component election from Regulation 1.168(k)-2(c), with the new dates swapped in. It lets you "treat an eligible component of an eligible larger self-constructed property as eligible" for the 100% deduction.
For a building, the regulation defines the "larger self-constructed property" as all the bonus-eligible property built as part of it. Those are the 5, 7, and 15-year pieces a cost segregation study pulls out. If construction of that larger property began before January 20, 2025, each component can still qualify on its own. Its acquisition must come after January 19, 2025, or work on it must start after that date.
On a long project, that can be a big share. Flooring, millwork, special lighting, and the parking lot may not have been bought or begun until 2025 or 2026. With the election, those components get 100%. The rest of the eligible basis stays on the old rules.
Three cautions. The election goes on a statement attached to the timely filed return, including extensions, for the year the larger property is placed in service. It says whether you're electing for all components or only some. And once made, it generally can be revoked only with a private letter ruling and the IRS's written consent. The one exception is a six-month window after the original due date, if the return was filed on time.
One open question. If the building slips into 2027, assume no bonus on any of it until your tax professional says otherwise. The component rules tie eligibility of the larger property to requirements that include the old placed in service deadline, and Notice 2026-11 doesn't speak to that case directly.
This is also where the quality of the study matters most. To split the basis, someone has to tie each component to an invoice, a change order, or a pay application with a date on it. An engineering-based study, with a trained professional walking the site in person and pricing components against the construction documents, can produce that trail. A rule-of-thumb percentage can't. I've written more on what engineering-based cost segregation looks like and which documents a study needs.
If I'm stuck on the old schedule, what do I actually get?
It depends on one date: when the property is placed in service.
Notice 2026-11 describes the 2017 law that still governs this property. Under it, bonus applied to qualified property "placed in service before January 1, 2027," and the rate "phased down by 20 percentage points annually." IRS Publication 946 (2025) confirms the rate for 2025: "you must take a 40% special depreciation allowance" for this property, unless you elect out. One more 20-point step gives 20% for property placed in service in 2026.
In 2027, the old law offers nothing. That placed-in-service deadline was in Section 168(k)(2)(A)(iii) of the 2017 version. The 2025 law struck it, but only for property acquired after January 19, 2025. For older property, the January 1, 2027 deadline still applies.
A narrow class of long production period property gets one extra year on the old schedule, with its own limits. Publication 946 describes it as property with a recovery period of at least 10 years, an estimated production period over one year, and an estimated cost over $1 million. Whether any part of your project fits is a question for your tax professional before you count on it.
Placed in service means ready and available for its intended use. It's not the closing date and not the day a tenant moves in. I covered that rule in depth in when a property is placed in service. For a project finishing this winter, that date is worth managing on purpose.
What does this look like with real numbers?
This is an illustration I built to show the mechanics, not a client's file.
Say an investor's contractor poured footings for a small office building in November 2024. That's before the cutoff, so the project is on the old rules. A cost segregation study finds $800,000 of 5, 7, and 15-year property. Of that, $300,000 is interior finishes and site paving that were contracted and started in 2026.
- Placed in service December 2026, with the component election: $300,000 at 100%, plus 20% of the other $500,000, or $100,000. First-year bonus: $400,000.
- Placed in service December 2026, no election: 20% of $800,000. First-year bonus: $160,000.
- Placed in service January 2027: plan on no bonus at all, for the reason in the open question above.
In every case, the study still matters. Components without bonus keep their 5, 7, or 15-year lives instead of 39 years, so the deduction still comes faster. It just doesn't all land in year one.
Now change one fact. Say the footings went in during February 2025, even though the construction contract was signed in 2024. Then all $800,000 qualifies for 100%, with no election needed. The difference between the two versions of this building is a date on a pour log, not a signature.
What should I do this month?
Four steps, in this order.
- Pull the paper. The signed purchase or construction contract, amendments, the dates any inspection or cancellation period ended, the date contingencies cleared, and for construction, the date of the first significant physical work.
- Have your tax professional set the acquisition date. Ask them to apply Regulation 1.168(k)-2(b)(5) with the Notice 2026-11 dates, and to look past the signature date.
- If construction started before the cutoff, find the components. A study can tie each component to dated invoices, so your tax professional can decide whether to make the component election.
- Know your placed in service date before December 31. For anything still on the old schedule, 2026 means 20% and 2027 means zero.
If you end up on the old schedule and the 20% doesn't fit your tax picture this year, electing out is still an option. I walked through when electing out of bonus depreciation makes sense.
Frequently Asked Questions
If I signed a purchase contract before January 20, 2025, am I stuck with the old bonus rates?
Not automatically. Under Treasury Regulation 1.168(k)-2(b)(5)(ii)(B), applied with the new dates by Notice 2026-11, the acquisition date is the latest of the signing date, the date the contract became enforceable, the end of any cancellation period, and the date all contingencies were met. A deal signed in December 2024 with an inspection period that ended in February 2025 can have a 2025 acquisition date.
Does the date I signed with my general contractor decide my bonus depreciation?
Usually not. Property built for you under a contract signed before work starts is treated as self-constructed, and it's dated by when physical work of a significant nature began. Planning, permits, and site clearing don't count. A safe harbor lets you use the date you paid or incurred more than 10 percent of the cost, excluding land.
Is a letter of intent a binding contract for bonus depreciation?
No. The regulation says a letter of intent for an acquisition is not a binding contract, and neither is an option to buy or sell. A contract that caps damages below 5 percent of the price also isn't binding under the rule.
What bonus depreciation do I get on pre-2025 property placed in service in 2026 or 2027?
Under the 2017 law that still governs property acquired before January 20, 2025, the rate is 20 percent for property placed in service in 2026. Property placed in service in 2027 gets no bonus depreciation, because the old law required qualified property to be placed in service before January 1, 2027. A narrow class of long production period property gets one extra year.
Can part of a building that started before the cutoff still get 100 percent?
Yes, through the component election in Section 3.05 of Notice 2026-11. Components acquired or started after January 19, 2025 can be treated as eligible for 100 percent, even if construction of the larger property began earlier. The election is made on a statement attached to the timely filed return for the year the property is placed in service.
Find out what your dates are worth
The rules in this post move real money, but only after someone knows what's in the building and when each piece arrived. That's where I can help. Want to know whether a study would even pay for itself on your property? That's what the no-cost analysis is for. It's delivered through my relationship with CSSI (Cost Segregation Services, Inc.). No obligation and no pitch. If a study won't pay for itself, I'll tell you so. You don't need to gather documents before we talk.
- Book a time: https://calendly.com/david-wiener/cs
- Or call 770-224-8504, option two.
You can see how the service works on the cost segregation page at davidhwiener.com. And if you haven't heard it yet, the full episode on bonus depreciation after the election puts this deadline next to the other two clocks that didn't care who won. If you're sorting out one of these dates right now, I'd like to hear which part of the rule is tripping you up.
Sources
- Public Law 119-21 (One Big Beautiful Bill Act), Section 70301(c), as reproduced in the notes to 26 U.S.C. 168.
- IRS Notice 2026-11, Interim Guidance on Additional First Year Depreciation Deduction under Section 168(k), Sections 2.01, 3.03, 3.05 and 6.02.
- Treasury Regulation 1.168(k)-2(b)(5) and (c), 26 CFR 1.168(k)-2.
- IRS Publication 946 (2025), How To Depreciate Property.
This article is educational and is not tax advice. Acquisition dates turn on the exact words of your contracts and the facts of your project. Talk to your own tax professional, and an attorney for contract questions, before acting on anything here.
CEO of Cashflow Strategies, Inc., Tax Strategist, Speaker, Educator
David “Mr. Cash Flow” Wiener is a nationally recognized authority on real estate tax strategy and cash flow optimization, and the host of The Tax Strategy Playbook podcast. As Founder and CEO of Cash Flow Strategies, Inc., David has spent decades helping real estate investors, business owners, and their advisory teams legally reduce taxes, unlock hidden cash flow, and put more money back into productive assets instead of into the IRS.
Over the course of his career, David has become especially known for his work with cost segregation, 179D energy-efficient commercial building deductions, and other engineering-based tax incentives that accelerate depreciation and free up capital. He has also built a long track record in cash flow and accounts receivable optimization, helping clients improve profitability and financial stability without simply “working harder” or taking on more risk.
David is a sought‑after speaker, trainer, and educator, with audiences ranging from national industry conferences to small mastermind groups and professional associations. He is known for his clear, practical teaching style and his ability to translate complex tax concepts into simple, actionable plays that investors and advisors can use right away. Whether he is speaking to CPAs, medical and dental practice owners, or real estate investors, David’s message is consistent: tax strategy is one of the most powerful—and most overlooked—wealth multipliers available.
On The Tax Strategy Playbook, David brings that same real‑world experience and teaching approach to the microphone. Each epis… Read More
5 Things a Tax Professional Should Expect From a Cost Segregation Firm