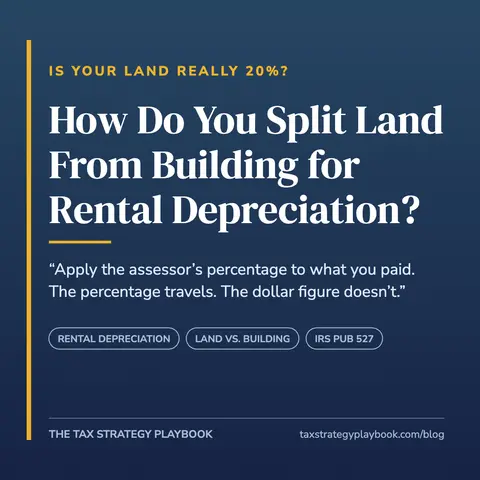
How Do You Split Land From Building for Rental Property Depreciation?
TL;DR
To split land from building for rental property depreciation, divide your total cost in proportion to the fair market value of each piece. If you aren't certain of those values, IRS Publication 527 lets you use the ratio of assessed values from your county's property tax records. Find the assessor's land value and improvement value for the year you bought, divide land by the total, and apply that percentage to what you paid. Never apply the assessor's dollar figure, and never default to a flat 20 percent. Land never depreciates, so this one split sets the size of your deduction every year for 27.5 years.
I walked through the whole depreciation calculation, from basis to the mid-month convention, in Episode 33 of The Tax Strategy Playbook: how rental property depreciation is calculated, line by line, with a duplex worked start to finish. This post takes one line of that calculation, the land split, and goes all the way down on it.
Key Takeaways
- Land can't be depreciated. Every rental purchase has to be divided into land, which you never deduct, and building, which you deduct over 27.5 years for residential or 39 for commercial.
- The rule is a fair market value ratio. The fallback in Publication 527 is the ratio of assessed values for real estate tax purposes.
- Apply the assessor's percentage to your cost. The assessor's dollar figure for land almost never matches your price.
- A flat 20 percent land figure is a habit, not a method. Land runs under 10 percent in some markets and over 85 percent in others.
- On a $406,000 duplex, the gap between 25 percent and 40 percent land is $60,900 of depreciation you never get to claim.
- Use the assessment roll that reflects your purchase, use gross values before exemptions, and save a dated screenshot.
Why does the land split matter so much?
Because it's the only input on your depreciation schedule that can quietly cost you money for 27.5 years without anyone noticing.
The tax code lets you deduct the building a slice at a time. It won't let you deduct the dirt. Publication 527 puts it plainly: "You can't depreciate the cost of land because land generally doesn't wear out, become obsolete, or get used up." So the moment you buy a rental, somebody has to decide how much of the price was land. Whatever number they pick comes straight off your depreciable basis, and the rest gets divided by 27.5 every year.
Here's the problem. Your settlement statement doesn't split the price. Neither does the purchase contract, in most deals. When a client hands a tax professional a closing statement and nothing else, the preparer has to use something, and a round percentage is what's available. Tax professionals work with what they're handed, and almost nobody hands them a land value. You can supply one in about five minutes.
What does the IRS say about splitting land and building?
Two sources, and they agree.
The regulation is Treasury Regulation 1.167(a)-5. When you buy depreciable and nondepreciable property together for one price, "as for example, buildings and land," the basis for depreciation "cannot exceed an amount which bears the same proportion to the lump sum as the value of the depreciable property at the time of acquisition bears to the value of the entire property at that time." In plain English, the building's share of your price matches the building's share of the property's value on the day you bought it.
IRS Publication 527 (2025), Residential Rental Property, turns that into instructions. "If you buy buildings and your cost includes the cost of the land on which they stand, you must divide the cost between the land and the buildings to figure the basis for depreciation of the buildings." The allocation is "the ratio of the FMV of that asset to the FMV of the whole property at the time you buy it." And then the sentence that matters for most rental owners: "If you aren't certain of the FMVs of the land and the buildings, you can divide the cost between them based on their assessed values for real estate tax purposes."
Publication 551, Basis of Assets (Rev. December 2025), says the same thing in shorter form: for a lump-sum purchase, "Figure the basis of each asset by multiplying the lump sum by a fraction."
Notice what the IRS did not say. It never mentions 20 percent. It never mentions any percentage. It gives you a method, and the method uses values tied to your property.
How do you use the county assessor's ratio?
This is the method I use on every property that comes across my desk. It takes about five minutes.
- Go to your county tax assessor's website and search by address or parcel number. If the assessor's page doesn't show the split, the county treasurer or tax collector's bill detail often does.
- Pick the right year. Use the assessment roll that reflects your purchase, not this year's. In a state that reassesses on a sale, such as California, that's the first roll after the county posts your purchase. For a rental you bought years ago, use the roll closest to your purchase date.
- Write down two numbers: the land value and the improvement value. "Improvements" is the assessor's word for the building.
- Use gross assessed values. Ignore homestead or other exemptions, which come off the total and have nothing to do with land.
- Divide land by land plus improvements. That's your land percentage.
- Multiply your total cost, purchase price plus the closing costs that belong in basis, by that percentage. That's land. The rest is your depreciable building basis.
- Take a screenshot of the assessor's page with the tax year showing, and save it with your closing statement.
Step six is where people go wrong, so here's what it looks like. Say the assessor shows land at $60,000 and improvements at $180,000, a total of $240,000. You paid $400,000 plus $6,000 of closing costs. The land isn't $60,000. The land is 25 percent, because $60,000 divided by $240,000 is 0.25, and 25 percent of $406,000 is $101,500. Assessed values almost never match what you paid. The percentage travels. The dollar figure doesn't.
Which closing costs belong in that $406,000? Publication 527 lists abstract fees, charges for installing utility services, legal fees, recording fees, surveys, transfer taxes, title insurance, and amounts the seller owed that you agreed to pay, like back taxes. Loan costs such as points and the lender's appraisal follow their own rules and stay out. Your tax professional sorts the settlement statement line by line.
Is 20 percent land a safe number to use?
No. It's a rule of thumb, and Publication 527 doesn't offer rules of thumb. It offers fair market value or the assessor's ratio. A flat 20 percent is neither one.
And land shares swing far more than most owners expect. When Ryan Bakke, CPA, joined me on Episode 10, on the short-term rental tax strategy, he said he'd never seen land worth more than 10 percent of a purchase in the Smokies. In Gulf Shores, he said, land on a single-family home runs 65 to 70 percent. Those are his observations from his own client work, not a survey, but they show the range. I've looked at a property in the Los Angeles area where the land came in at 87.5 percent. One I ran recently came in at 97 percent.
Put 20 percent on that last house and you're claiming depreciation on dirt. Put 20 percent on a cabin in the Smokies and you're leaving deductions on the table every year for 27.5 years. The guess is wrong in both directions. That's the problem with it.
What does a wrong land split cost you?
Run the numbers on one property and the answer gets concrete fast. This is an illustration, not a client.
A duplex costs $400,000. Closing costs that belong in basis add $6,000, for a total of $406,000. The assessor's ratio says 25 percent land.
| Land figure used | Land | Building basis | Depreciation per full year (27.5 years) |
|---|---|---|---|
| Assessor's ratio, 25% | $101,500 | $304,500 | about $11,073 |
| Flat guess, 20% | $81,200 | $324,800 | about $11,811 |
| Someone typed 40% | $162,400 | $243,600 | about $8,858 |
The 40 percent row costs about $2,215 of depreciation every year. Over the full 27.5 years, that's $60,900 of deductions that never appear on any return you file. One number typed into one box.
The 20 percent row looks like a win until you ask what's behind it. That return claims about $738 a year more than the assessor's ratio supports, which adds up to $20,300 of depreciation taken on land. If the allocation is ever questioned, the supported number is the assessor's, not the round one, and you'd be defending a figure with nothing behind it.
And remember where depreciation ends up. Every dollar of it lowers your basis, and when you sell, the IRS settles up. So the split doesn't only change what you deduct. It changes the math at the sale too, which is covered in what happens when you sell a property after cost segregation.
When shouldn't you trust the assessor's split?
The assessor's ratio is the IRS-sanctioned fallback, not a perfect answer. Three situations call for a second look.
A frozen formula. Some counties set the land share by formula and carry it forward for years. The usual tell is an exact 50/50 split that hasn't moved across a decade of tax rolls. It's still the accepted assessed-value method and you can use it. Just know it's a formula, not a fresh appraisal.
A sale the county hasn't posted yet. If you bought recently in a state that reassesses on a sale, the newest roll may still show the prior owner's values. Use the newest roll you have, note it, and check again once the county updates.
Better evidence of fair market value. The assessor's ratio is the method for when "you aren't certain" of the fair market values. An appraisal that values the land and the building separately is direct evidence of fair market value, and it outranks the fallback. So does a land value that an engineering-based cost segregation study documents as part of its allocation. If you've got one of those, use it.
What doesn't count as better evidence is a number someone likes. If you think the county's land figure is too high, the fix is an appraisal, not a smaller percentage typed in by hand.
Does "land" include the driveway and the landscaping?
Partly, and this is where land and land improvements get confused.
IRS Publication 946 (2025), How to Depreciate Property, says "the cost of land generally includes the cost of clearing, grading, planting, and landscaping." Those costs sit with the land and don't depreciate. Shrubbery planted right around a building is the exception the publication carves out, because it's closely tied to the building.
Things built on the land are different. Driveways, sidewalks, fences, and parking areas are land improvements, generally 15-year property. On a standard depreciation schedule they get lumped into the building and depreciated over 27.5 or 39 years. Pulling them out is a separate job, and what counts as a land improvement, and why it depreciates over 15 years covers it. For the land split, the point is narrower. The assessor's land value is the dirt. Don't move your driveway into it.
What if you converted your home or inherited the rental?
You still split land from building. What changes is the number you're splitting.
If you lived in the home and then rented it out, Publication 527 says the basis for depreciation is "the lesser of its adjusted basis or its FMV" when you change it to rental use. You figure that number first, then apply the land split to it, using the assessor's ratio closest to the date of the change.
If you inherited it, Publication 551 says the basis is generally "the FMV of the property at the date of the individual's death." Get that value in writing, usually from an appraisal. If the appraisal values land and building separately, that's your split. If not, use the assessor's ratio for the roll nearest the date of death.
Both cases have more to them than the land split. Bring them to your tax professional with the dates and the paperwork in hand.
Frequently Asked Questions
How do I find the land value of my rental property?
Look up your property on the county tax assessor's website by address or parcel number. The assessment shows a land value and an improvement value. Divide the land value by the total to get the land percentage, then apply that percentage to what you paid.
Can I use 20 percent for land on my rental?
IRS Publication 527 doesn't provide a flat percentage. It says to allocate by fair market value, or by assessed values for real estate tax purposes if you aren't certain of fair market value. Land shares vary from under 10 percent to over 85 percent depending on location, so a flat 20 percent can be wrong in either direction.
Do I use the assessor's dollar value for land?
No. Use the assessor's ratio, not the dollar figure. Assessed values rarely match your purchase price. Divide assessed land by total assessed value, then apply that percentage to your total cost.
Which year's assessment should I use?
Use the assessment roll that reflects your purchase, not the current year. In a state that reassesses on a sale, that's the first roll after the county posts your purchase. For an older purchase, use the roll closest to the purchase date.
Do closing costs get split between land and building too?
Yes. Closing costs that belong in basis, such as title insurance, recording fees, legal fees, surveys and transfer taxes, are part of your total cost. You apply the land percentage to the purchase price plus those costs.
Is an appraisal better than the assessor's ratio?
An appraisal that values land and building separately is direct evidence of fair market value, which is the primary rule in Publication 527. The assessor's ratio is the fallback for when you aren't certain of fair market value.
Where to go from here
Pull up your county assessor's site tonight and look at one property. Then pull your depreciation schedule and see what land figure is on it. If those two numbers are close, you're done. If they aren't, take the screenshot to your tax professional and ask how the original number was set. How a long-running wrong split gets corrected depends on your facts and how many years have been filed, so that's their call, not a number to change yourself.
If you'd like the rest of the calculation, the placed in service date, the mid-month convention and the duplex worked all the way through, listen to Episode 33 for the full line-by-line walkthrough of rental property depreciation.
And once you know your real building basis, you can ask the next question. If you own a building that cost $150,000 or more, a short call will tell you whether an engineering-based cost segregation study is worth doing. The analysis is no-cost and delivered through my relationship with CSSI, it comes with no obligation and no pitch, and if the numbers don't work, I'll say so. Book a time at calendly.com/david-wiener/cs or call 770-224-8504, option two.
What land percentage did you find on yours? I'd like to hear how far off the round number was.
Nothing here is tax advice for your situation. Your numbers are your numbers, and they need a professional who knows them.
CEO of Cashflow Strategies, Inc., Tax Strategist, Speaker, Educator
David “Mr. Cash Flow” Wiener is a nationally recognized authority on real estate tax strategy and cash flow optimization, and the host of The Tax Strategy Playbook podcast. As Founder and CEO of Cash Flow Strategies, Inc., David has spent decades helping real estate investors, business owners, and their advisory teams legally reduce taxes, unlock hidden cash flow, and put more money back into productive assets instead of into the IRS.
Over the course of his career, David has become especially known for his work with cost segregation, 179D energy-efficient commercial building deductions, and other engineering-based tax incentives that accelerate depreciation and free up capital. He has also built a long track record in cash flow and accounts receivable optimization, helping clients improve profitability and financial stability without simply “working harder” or taking on more risk.
David is a sought‑after speaker, trainer, and educator, with audiences ranging from national industry conferences to small mastermind groups and professional associations. He is known for his clear, practical teaching style and his ability to translate complex tax concepts into simple, actionable plays that investors and advisors can use right away. Whether he is speaking to CPAs, medical and dental practice owners, or real estate investors, David’s message is consistent: tax strategy is one of the most powerful—and most overlooked—wealth multipliers available.
On The Tax Strategy Playbook, David brings that same real‑world experience and teaching approach to the microphone. Each epis… Read More
If a Client Paid for the Work, Can You Still Claim the R&D Tax Credit?